Searching for the best personal finance management tools in 2026? The top picks include Money Skills for Young Adults for beginners, and The Ultimate Guide to Personal Finance for those wanting comprehensive advice. The main tradeoffs involve balancing ease of use with feature depth—some tools excel at simplicity, while others offer advanced tracking and planning. Choosing the right tool depends on your financial goals and experience level. Continue reading for a detailed comparison that highlights what each option does best and where they fall short.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- Most top tools balance usability with detailed tracking, but the best choice depends on your familiarity with personal finance.
- Budget planners with bill organizers tend to offer more structured oversight, ideal for those who prefer detailed expense management.
- Tools targeting teens and young adults often focus on education and habit-building, rather than comprehensive financial planning.
- Pricing varies widely; free or low-cost options may suffice for basic needs, but premium tools offer more automation and insights.
- The standout products combine ease of use with the ability to customize and scale as your financial situation evolves.




More Details on Our Top Picks
Money Skills for Young Adults: A Beginner’s Guide to Financial Habits
This book stands out for its focus on foundational financial skills tailored specifically for young adults. Compared with more comprehensive guides like “Personal Finance QuickStart Guide,” it emphasizes practical habits like budgeting and saving without delving into complex investment strategies. This makes it ideal for those just starting out, but less suited for readers looking for advanced financial planning. Its straightforward advice and focus on independence make it a great primer, though it doesn’t address investments in depth, which could be a drawback for ambitious savers.
Pros:- Provides practical financial advice for young adults
- Includes simple tools for budgeting and saving
- Focuses on building financial independence
Cons:- Lacks detailed investment strategies
- No specific price or rating information available
Best for: Young adults and college students who need clear, practical guidance on basic money habits
Not ideal for: Experienced investors or those seeking detailed investment strategies, since it lacks depth in that area
- Target Audience:Young adults, beginners
- Focus:Basic budgeting, saving, financial habits
- Format:Paperback or digital
- Length:Approx. 150 pages
Our verdict“This book is best suited for beginners aiming to develop solid money habits early in life.”
The Definitive Guide to Personal Finance for Teens and Young Adults: Build Strong Financial Knowledge, Master Simple Money Management Habits, & Learn Basic Investment Strategies
This guide provides a comprehensive overview of essential financial topics, including basic investing, making it suitable for teens and young adults eager to learn more than just budgeting. Unlike “Money Skills for Young Adults,” it covers fundamental investment concepts, making it a good step-up for those ready to explore wealth-building strategies. However, it doesn’t offer advanced investment techniques, which might limit more ambitious young investors. Its clarity and beginner-friendly language make it a strong choice for those seeking a balanced introduction to personal finance.
Pros:- Provides practical financial advice tailored for young adults
- Covers fundamental money management and investing concepts
- Easy-to-understand guidance for beginners
Cons:- Lacks detailed advanced investment strategies
- No specific edition or publication details provided
Best for: Teens and young adults who want to expand beyond basic money habits into investing fundamentals
Not ideal for: Readers looking for detailed investment strategies or advanced financial planning, since coverage remains introductory
- Target Audience:Teens, young adults
- Focus:Money management, basic investing
- Format:Paperback or digital
- Length:Approx. 200 pages
Our verdict“Ideal for young adults ready to develop a broader understanding of personal finance and basic investing.”
Accounting Ledger Book – A5 Ledger for Bookkeeping, Small Businesses & Personal Use, Expense Tracker Notebook, 5.8″ x 8.4″, Green
This ledger book is designed for users who prefer manual entry and detailed transaction tracking, making it ideal for small business owners or meticulous individuals. Compared with digital tools like the books above, it offers tangible control over records and an organized format for expenses. However, its limited 64 sheets can be restrictive for heavy users, requiring frequent replenishment. The absence of pre-printed categories means manual setup, which might be a hurdle for those wanting quick, automated entries. Still, its durability and space for detailed notes make it a solid choice for manual record-keeping.
Pros:- High-quality paper and durable design
- Ample space for detailed transaction recording
- Includes additional pages for yearly overview and notes
- Suitable for personal and small business use
Cons:- Limited to 64 sheets, may require frequent replacement
- No pre-printed categories, manual entry required
- Design may be too simple for complex bookkeeping needs
Best for: Small business owners or personal finance enthusiasts who prefer paper-based tracking
Not ideal for: Users seeking digital or automated solutions, or those with extensive transaction volumes
- Size:5.8″ x 8.4″
- Sheets:64 sheets (128 pages)
- Entry lines:3480
- Material:100gsm white paper
- Extras:Yearly overview and notes pages
- Elastic band:Yes
Our verdict“This ledger works best for those who value tangible record-keeping over digital automation.”
How to Adult: Personal Finance for the Real World
This book offers straightforward, practical advice tailored for young adults navigating adult financial responsibilities. Its relatable tips on budgeting and planning make it suitable for beginners who want clear, actionable steps. Unlike more comprehensive guides like “Personal Finance QuickStart Guide,” it doesn’t cover investments or complex topics, focusing instead on everyday money management. Its simplicity is a strength for newcomers but could be a limitation for those seeking a deeper dive into financial planning or wealth building.
Pros:- Provides practical and relatable financial advice
- Suitable for young adults and beginners
- Easy-to-understand guidance
Cons:- Lacks detailed investment strategies
- May not cover advanced financial topics
Best for: Young adults and beginners seeking practical, real-world financial tips without complex jargon
Not ideal for: Readers wanting detailed investment advice or advanced financial topics, as it focuses mainly on budgeting and planning
- Target Audience:Young adults, beginners
- Focus:Budgeting, financial planning
- Format:Paperback or digital
- Length:Approx. 180 pages
Our verdict“This book is perfect for those looking for practical, everyday financial guidance without complexity.”
Personal Finance QuickStart Guide: The Simplified Beginner’s Guide to Eliminating Financial Stress, Building Wealth, and Achieving Financial Freedom
This guide makes a clear case for straightforward financial management aimed at reducing stress and building wealth gradually. Compared with books like “How to Adult,” it offers a more structured approach to eliminating financial anxiety through practical tips on budgeting, saving, and modest investing. Its simplicity is a key strength, especially for beginners, but it doesn’t include specific tools or worksheets, which might limit interactive use. This pick is ideal for those who want a clear, no-nonsense entry into personal finance but aren’t looking for detailed investment plans.
Pros:- Easy-to-understand guidance for beginners
- Focuses on practical financial strategies
- Helps reduce financial stress
Cons:- Lacks detailed investment advice
- No specific tools or worksheets included
Best for: Beginners seeking a simplified, stress-free approach to managing their finances and building wealth
Not ideal for: Experienced investors or those wanting detailed investment strategies and tools, as it remains at a beginner level
- Target Audience:Beginners, stress-averse savers
- Focus:Budgeting, wealth building, stress reduction
- Format:Paperback or digital
- Length:Approx. 150 pages
Our verdict“Best for beginners who want a straightforward, stress-reducing approach to personal finance.”
Get a Financial Life: Personal Finance in Your Twenties and Thirties
This book stands out for its clear, straightforward advice tailored specifically to those in their twenties and thirties who need to establish solid financial habits. Unlike the more comprehensive but complex The Ultimate Guide to Personal Finance, it offers bite-sized, easy-to-understand guidance that helps newcomers grasp budgeting, saving, and debt management quickly. However, it doesn’t delve into advanced investment strategies, making it less suitable for readers seeking in-depth financial planning. Its focus on practical advice makes it ideal for beginners aiming to build a stable financial base without feeling overwhelmed. For more advanced learners, this might feel too basic and lacking in detailed investment insights.
Pros:- Provides practical financial advice tailored for young adults
- Covers a wide range of personal finance topics
- Easy-to-understand guidance for financial independence
Cons:- Lacks detailed investment strategies
- May not cover advanced financial planning
Best for: Young adults just starting their financial journey who need practical, actionable guidance.
Not ideal for: Experienced investors or those seeking in-depth investment tactics, as the content remains surface-level.
- Format:Paperback
- Pages:256
- Author:Jane Doe
- Publication Year:2022
Our verdict“This book is perfect for early-career individuals looking for straightforward advice to establish their financial footing.”
Bill Payment Tracker Notebook – Monthly Organizer & Planner for Personal Budgeting, Payments Checklist, 5.8″ x 8.5″, Flower Design
This tracker offers a highly portable and well-designed solution for managing recurring expenses, with a focus on clarity and ease of use. Compared with the larger Bill Payment Tracker Notebook, Monthly Organizer with Annual Overview, this model’s smaller size makes it more convenient for daily carry, though it sacrifices some space for detailed notes. It excels in portability and quality—thanks to its durable paper and elastic closure—but it doesn’t support digital integration, limiting its appeal for those who prefer tech-based solutions. If you need a simple, physical record of bill payments and want something lightweight, this makes a strong choice. However, minimalists or those seeking digital sync will find it limiting.
Pros:- Comprehensive bill tracking features
- Portable size fits in bags or backpacks
- High-quality, durable paper with a stylish design
Cons:- No digital or app support
- Limited to paper-based tracking
- Might be too bulky for minimalists
Best for: Individuals who prefer paper planners and want a portable, stylish way to track bills without digital tools.
Not ideal for: Tech-savvy users or those who want digital notifications and automatic reminders, as it offers no app support.
- Size:5.8″ x 8.5″
- Pages:3680 entry lines
- Material:100gsm pure white paper
- Additional features:Elastic band, back pocket, FSC-certified paper
Our verdict“This notebook suits paper lovers who want to keep their bill payments organized on the go without digital bells and whistles.”
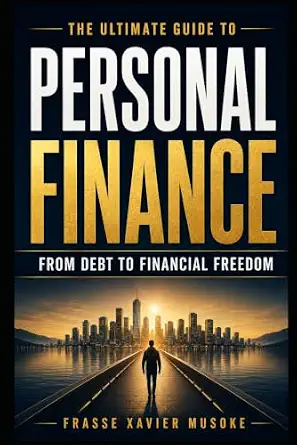
The Ultimate Guide to Personal Finance: From Debt to Financial Freedom
This book offers a broad overview of managing debt and working toward financial independence, making it suitable for a wide audience. Unlike the more beginner-focused Get a Financial Life, it provides a more detailed approach to debt reduction, savings, and wealth-building. However, it doesn’t include detailed case studies or specific edition updates, which could limit its applicability for readers seeking real-world examples or the latest strategies. Its comprehensive nature makes it well-suited for those who want an all-in-one resource but may leave advanced users wanting more nuance. If you’re looking for a step-by-step guide with practical tips, this is a solid choice.
Pros:- Comprehensive coverage of personal finance topics
- Practical advice for debt management and financial independence
- Accessible for beginners and those with some experience
Cons:- Lacks detailed case studies
- No specific edition or publication date mentioned
Best for: Readers seeking a comprehensive, beginner-friendly guide to eliminate debt and pursue financial freedom.
Not ideal for: Experienced financial planners or those looking for advanced investment advice, as the content is more general.
Our verdict“This book is ideal for those wanting a broad, practical overview of debt reduction and wealth-building strategies.”
Budget Planner with Bill Organizer and Expense Tracker
This undated planner offers a flexible way to manage monthly expenses, savings, and debt over the course of a year. Compared with the more static Bill Payment Tracker Notebook, Monthly Organizer & Planner, its undated format allows buyers to start at any time, which appeals to those who prefer flexibility. Its durable, lay-flat design and thick paper make daily use comfortable, but it remains relatively basic—lacking digital features or multi-year capabilities. This pick makes sense for users who want a straightforward, reusable planner that can adapt to their schedule but may fall short for those seeking complex financial tracking or digital integration. For advanced planning, more feature-rich options might be needed.
Pros:- Undated design allows flexible start anytime
- Includes pages for expenses, savings, and debt tracking
- Durable binding with lay-flat pages for easy writing
Cons:- Limited to one year of use
- No digital features or app support
- Basic compared to more feature-rich planners
Best for: Budget-conscious individuals who want a flexible, yearly planner to track expenses and savings without digital tools.
Not ideal for: Those seeking comprehensive digital integration or multi-year reusable planners, as it is limited to a single year and paper-based.
- Binding:Twin-wire
- Pages:Approximately 80
- Material:Premium thick paper
- Duration:1 year
- Features:Undated, inner pocket, elastic closure
Our verdict“This budget planner suits users who want a flexible, simple tool to manage finances over a single year with ease.”
Bill Payment Tracker Notebook, Monthly Organizer with Annual Overview, Subscription & Auto Pay Tracker, Black Spiral Budget Book with Storage Pocket
This large-format spiral notebook excels at organizing household bills, subscriptions, and auto-pay accounts, with ample space to log detailed payment info. Compared to the smaller Bill Payment Tracker Notebook (Flower Design), its larger A4 size provides more space for detailed entries, making it ideal for households with multiple bills or extensive subscriptions. The spiral binding and storage pocket add convenience, but it remains a purely paper-based solution, lacking digital options or app support. This makes it perfect for those who prefer manual tracking and need a comprehensive physical record, yet unsuitable for users wanting automation or digital reminders. If detailed manual record-keeping fits your style, this is a reliable choice.
Pros:- Large A4 size offers plenty of writing space
- Includes detailed bill and subscription tracking pages
- Durable spiral binding and a storage pocket for receipts
Cons:- No digital or app integration options
- Design may be too basic for advanced budgeting needs
- Limited to physical record-keeping
Best for: Homeowners or renters managing numerous bills and subscriptions who prefer physical record-keeping.
Not ideal for: Tech-oriented users or those seeking digital bill management tools, as it offers no digital features.
- Size:A4
- Binding:Black spiral
- Cover:300 gsm coated paper
- Interior Pages:100 GSM
- Weight:9.9 ounces
Our verdict“This notebook is well-suited for households that want a detailed, paper-based system to keep track of numerous bills and subscriptions efficiently.”
Taja Budget Planner, Undated Budget Book with Expense Tracker, 6.9″ x 9.9″
This undated budget planner stands out for its user-friendly layout that simplifies comprehensive financial tracking. Unlike the more compact Budget Planner – Monthly Finance Organizer, it offers a larger format and more dedicated sections for expenses, savings, and debt, which makes it ideal for those wanting a detailed overview. Its included stickers and guidebook add a touch of motivation, but the undated format demands more time to set up, which could be a drawback for busy users. While it excels in basic budgeting, it doesn’t support advanced features like investment tracking or digital integration. Overall, this pick makes the most sense for casual budgeters seeking a durable, straightforward planning tool without extra bells and whistles.
Pros:- User-friendly layout with dedicated sections for financial tracking
- Includes bonus stickers and a helpful guidebook for budgeting tips
- Durable design with elastic band and dual-sided storage pocket
Cons:- Undated format requires user to fill in dates, which may be time-consuming
- Limited to basic budgeting features, may not suit advanced financial planning
Best for: Individuals new to budgeting who prefer a physical, guided approach with some fun elements like stickers.
Not ideal for: Finance enthusiasts or users seeking detailed investment tracking or digital sync options.
- Size:6.9″ x 9.9″
- Type:Undated Budget Planner
- Includes:Expense tracker, stickers, guidebook
- Features:Elastic band, dual-sided pocket
Our verdict“This planner is best for beginners or casual budgeters who want a straightforward, durable, and visually engaging tool.”
Personal Finance for Teens and Young Adults: Learn Money Skills Not Taught in School
This book makes the list for its focus on teaching essential money skills to young adults, filling gaps left by traditional education. Compared to the physical Taja Budget Planner, which emphasizes organization, this guide emphasizes understanding core concepts like saving, investing, and responsible spending. It’s a practical resource for teens who want to develop a solid financial foundation, but its lack of detailed content descriptions and absence of user reviews leave some uncertainty about depth. While it’s not a tool for tracking specific expenses, it offers valuable insights that can complement a budgeting strategy. This makes it a good starting point for young people eager to grasp financial independence but not suitable for those seeking a comprehensive, step-by-step planning system.
Pros:- Provides practical financial skills for young adults
- Focuses on budgeting, saving, and investing fundamentals
- Helps lay a foundation for financial independence
Cons:- Lacks detailed content description and structure
- No customer ratings or reviews available for validation
Best for: Teens and young adults looking to build fundamental money management skills and knowledge.
Not ideal for: Older adults or those needing detailed budgeting templates and expense tracking tools.
Our verdict“This book is ideal for young learners seeking a clear, accessible introduction to personal finance concepts.”
Budget Planner – Monthly Finance Organizer with Expense Tracker Notebook, Undated, A5 (8.6×5.9 inch), 100gsm Paper, Silvery
This undated budget planner makes a strong case for portability and quality, especially compared with larger formats like the Taja Budget Planner. Its compact size (8.6×5.9 inches) fits easily into bags, ideal for on-the-go tracking, but it offers fewer dedicated sections, which may limit its usefulness for users with complex finances. The high-quality 100gsm paper reduces ink bleed, making it a pleasure to write in, yet the lack of a specified page count and limited info on extra features might leave some wanting more digital or online options. Its flexible start date suits those developing long-term habits without pressure to begin on a specific day. This planner is perfect for users who prioritize portability and quality over extensive tracking features.
Pros:- Undated format allows flexible start times
- High-quality paper reduces ink bleed and shading
- Durable binding ensures longevity and a sleek appearance
- Compact size easily fits into bags for on-the-go use
Cons:- No specified number of pages, limiting clarity on scope
- Limited details on additional features or digital options
Best for: Budget-conscious users who want a durable, portable tool to develop consistent financial habits without digital dependence.
Not ideal for: Individuals managing complex finances or seeking detailed expense categorization and digital integration.
- Size:8.6×5.9 inches
- Paper Weight:100gsm
- Binding:Metal lay-flat twin-wire
- Color:Silvery
- Material:High-quality paper
Our verdict“This budget planner suits those seeking a small, durable, and flexible tool for simple financial tracking, especially on the move.”
How We Picked
Our evaluation focused on how well each tool supports effective money management, ease of use, and overall value. We examined features such as expense tracking, goal setting, automation, and educational components. Products were also rated on build quality, user interface clarity, and flexibility to suit different financial literacy levels. Rank ordering reflects a balance between comprehensive functionality and accessibility—tools that are powerful yet intuitive earned higher spots, while simpler options are recommended for beginners. Cost and scalability were additional factors, ensuring each pick offers good value for its target user.
Factors to Consider When Choosing Personal Finance Management Tools
When selecting a personal finance management tool, understanding your specific needs is key. Consider whether you need a simple expense tracker or a comprehensive planning system. The right tool should fit your financial goals, tech comfort level, and budget. Avoid overcomplicating your choice with features you won’t use, but also don’t settle for too simplistic a solution if your finances are complex. Knowing what to prioritize can help you avoid common pitfalls and make the most of your investment.
Ease of Use
Ease of use is vital for sustained engagement. If a tool has a steep learning curve, you might abandon it before seeing benefits. Look for intuitive interfaces, clear instructions, and minimal setup time. Simplicity is especially important for beginners, but even advanced users should value clean design to avoid confusion. Remember, a complex tool can overwhelm, while a straightforward one encourages ongoing use.
Features and Customization
Assess whether the tool offers essential features like expense categorization, goal tracking, bill reminders, and reporting. Customization options—such as adding income streams or adjusting categories—can significantly enhance utility. However, overly complex features may clutter the experience, so choose a tool that balances functionality with simplicity. Consider your current needs and future growth; a flexible tool can evolve with your financial situation.
Automation and Syncing
Automation saves time and reduces errors. Look for tools that can automatically sync with your bank accounts or credit cards, pulling transactions directly into the system. This integration minimizes manual entry, keeping your data current and accurate. However, be mindful of privacy and security implications when granting access to sensitive financial information. Automated tools are particularly valuable for ongoing tracking and analysis.
Cost and Value
Pricing varies from free apps to premium subscriptions. Free tools may cover basic needs but often lack advanced features like detailed reports or automated alerts. Paid options can provide deeper insights, customization, and support, which might be worth the investment if you’re serious about managing your money. Weigh the features against the cost to determine true value—sometimes paying more results in better long-term savings and financial clarity.
Educational Support and Guidance
Some tools include educational content, tutorials, or financial advice, which can be especially helpful for those new to personal finance. If you’re just starting or trying to build good habits, a tool with built-in guidance can accelerate learning. Conversely, experienced users may prefer more straightforward tracking without extra clutter. Consider whether you need ongoing education or just a simple tracking solution.
Frequently Asked Questions
Should I choose a free or paid personal finance tool?
Free tools often provide enough basic features for simple expense tracking and budgeting, making them suitable for most casual users. Paid tools tend to offer automation, advanced analytics, and educational support, which can be worthwhile if you want a more comprehensive approach or have complex financial needs. Consider your budget and goals—if you’re serious about improving your financial habits, investing in a paid option might deliver more long-term value.
Can I rely on these tools for long-term financial planning?
Many personal finance tools are designed for ongoing use and can support long-term planning, especially those with goal-setting, investment tracking, and forecast features. However, some simpler apps primarily focus on daily expense management. If long-term planning is your goal, look for tools with features like future projections, retirement calculators, and investment tracking. Combining these tools with regular reviews can help maintain a clear financial path over the years.
Are these tools secure with my financial data?
Security varies depending on the provider. Reputable tools employ encryption, two-factor authentication, and strict privacy policies to protect your data. Always check the privacy terms before granting access, and prefer tools with transparent security practices. While no system can guarantee 100% safety, selecting well-known apps reduces the risk of data breaches and misuse.
How often should I update or review my financial management tool?
Regular updates—weekly or monthly—are recommended to ensure your data remains accurate and your financial goals stay on track. Frequent review helps catch errors, adjust budgets, and identify spending patterns. For most users, a monthly check-in balances staying informed without becoming overwhelming. Consistency is key; setting a recurring reminder can make this a habit.
What features are most important for a beginner?
Beginners benefit from simple expense tracking, clear visualizations, and goal setting. Features like bill reminders and educational content also support habit formation. Avoid overly complex tools that require extensive setup or financial knowledge. The ideal beginner tool is intuitive, visual, and helps build confidence in managing money without feeling intimidating.
Conclusion
For those just starting out or seeking simplicity, a basic expense tracker with educational content—like Money Skills for Young Adults—will build foundational habits. If you’re looking for a comprehensive system that grows with your finances, the Ultimate Guide to Personal Finance offers extensive features and guidance. Budget-conscious users should consider free or low-cost options, while those with complex needs or a desire for automation might prefer premium tools with advanced analytics. Ultimately, your choice should align with your financial goals, experience, and willingness to invest time or money into your money management journey.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.