TL;DR

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
A Roth conversion moves pretax retirement money into a Roth IRA and generally adds the converted amount to taxable income for that year. Kiplinger’s report says whether it makes sense depends on individual circumstances, including current and future tax exposure, conversion size and timing; future tax rates and policy remain uncertain.
A Kiplinger report on Roth conversions says the decision depends on when to convert and how much, because moving pretax retirement savings into a Roth IRA generally creates a tax bill in the conversion year. The choice matters because paying tax now may reduce taxable withdrawals later, but a large conversion can also raise current-year income and affect other tax-related costs.
A Roth conversion moves money from a pretax account, such as a traditional IRA or, in some cases, a 401(k), into a Roth IRA. The report says the portion that has not already been taxed is generally included in ordinary taxable income for the year of conversion. Its example: converting $20,000 from an entirely pretax IRA, with those dollars falling in the 22% federal bracket, could add about $4,400 in federal income tax. That is an illustration, not an estimate for every taxpayer; deductions, state taxes, other income and any after-tax IRA funds can change the result.
The trade-off is between paying tax on the converted amount now and keeping the money in a tax-deferred account. Traditional IRA withdrawals are generally taxable as ordinary income. Roth assets can grow in the account, and qualified Roth distributions can be withdrawn free from federal income tax. Roth IRAs also do not require minimum distributions during the original owner’s lifetime, according to the report.
Converting too much in one year could push income into a higher tax bracket or affect other costs tied to income. The report points to potential effects on Medicare premiums through IRMAA and the taxation of Social Security benefits, among other tax considerations. It argues that reducing pretax balances may help manage future taxable income, but the result depends on a person’s full financial and tax circumstances.
How Conversion Size Affects Retirement Taxes
The decision can change the timing of taxes across a retirement plan. A conversion means paying tax on some savings before they are withdrawn, in exchange for the possibility of less taxable income from those assets later. Whether that trade works depends in part on the tax rate applied now compared with the rate that would apply to future withdrawals; neither future income nor future tax policy is certain.
The amount converted matters as much as the decision to convert. A partial conversion may limit the immediate income increase, while a larger one could have knock-on effects in the conversion year. The report’s central point is not that one approach is always preferable, but that savers need to weigh the current tax cost against possible future benefits using their own income, account mix and retirement plans.
Products Worth Considering
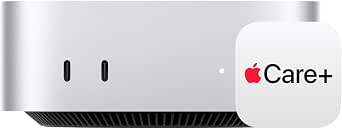
Apple Mac mini (2026) with M5 Pro chip and 3-year AppleCare+

Samsung 34-Inch ViewFinity S50GC Ultra-WQHD Monitor

Apple MacBook Pro 14 2021 with M1 Max, 64GB RAM, 2TB SSD, Silver
As an affiliate, we earn on qualifying purchases.
The Tax Trade-Off Behind Roth Conversions
The report frames conversion decisions against the tax rules in effect now and uncertainty about future policy. It states that the highest federal individual income tax rate for 2026 is 37% and compares that with higher top rates in some earlier periods. That history provides context, but it does not establish that rates will rise or predict what any individual’s future tax rate will be.
It also cites long-range pressures on retirement programs. The report says the Census Bureau projects about 77 million Americans age 65 and older by 2034. It attributes to the 2026 Social Security Trustees Report a projection that combined trust fund reserves would be sufficient to pay scheduled benefits until 2034, with continuing program income then covering about 83% of scheduled benefits if no changes were made. That projection does not mean Social Security would disappear in 2034, and it does not settle what lawmakers might do about benefits or funding.
““The answer to all of them … is it depends.””
— Kiplinger report
Future Tax Rates Remain Unknown
Several inputs that could determine whether a conversion pays off are uncertain: a person’s future income, applicable tax rates, investment growth and retirement spending needs. The report does not establish that federal tax rates will increase, nor does it predict how Congress might change tax rules, Social Security or Medicare. Program projections also depend on assumptions and policy responses.
The supplied report material does not provide a personalized conversion calculation, a universal recommended amount or a complete account of every household’s tax circumstances. The example using a $20,000 conversion is illustrative. Readers’ actual tax bills may differ based on their full income, deductions, state taxes and whether some IRA contributions were made with after-tax dollars.
What Savers Should Weigh Before Converting
The next step is to compare the immediate tax cost of a proposed conversion with the possible effect on future taxable withdrawals. That requires estimating income for the conversion year, identifying the pretax portion of accounts and considering whether added income could affect tax brackets, Medicare premiums or Social Security taxation. The report recommends thinking about how much and when, rather than treating conversion as an all-or-nothing choice.
Future tax and benefit rules may change, but the report gives no date or specific policy change to watch for. Any decision should account for current rules and a person’s own circumstances; the source does not offer a single answer that applies to all savers.
Key Questions
What is a Roth conversion?
It is a transfer of money from a pretax retirement account, such as a traditional IRA or, in some cases, a 401(k), into a Roth IRA. The untaxed portion is generally added to taxable income for the conversion year.
How much tax might a conversion create?
The report’s example says converting $20,000 of entirely pretax IRA money could create about $4,400 in federal income tax if those dollars fall within the 22% bracket. That is only an illustration; the actual amount depends on a person’s full tax situation.
It can. The report says higher income in the conversion year may affect Medicare premiums through IRMAA and how much of a person’s Social Security benefits is taxable. The effect depends on individual circumstances.
Does the report say taxes will definitely rise?
No. It discusses current rates and historical comparisons, but says future tax policy is uncertain. Historical rates do not establish what lawmakers will do or what rates will apply to a particular saver.
Source: kiplinger.com