TL;DR

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
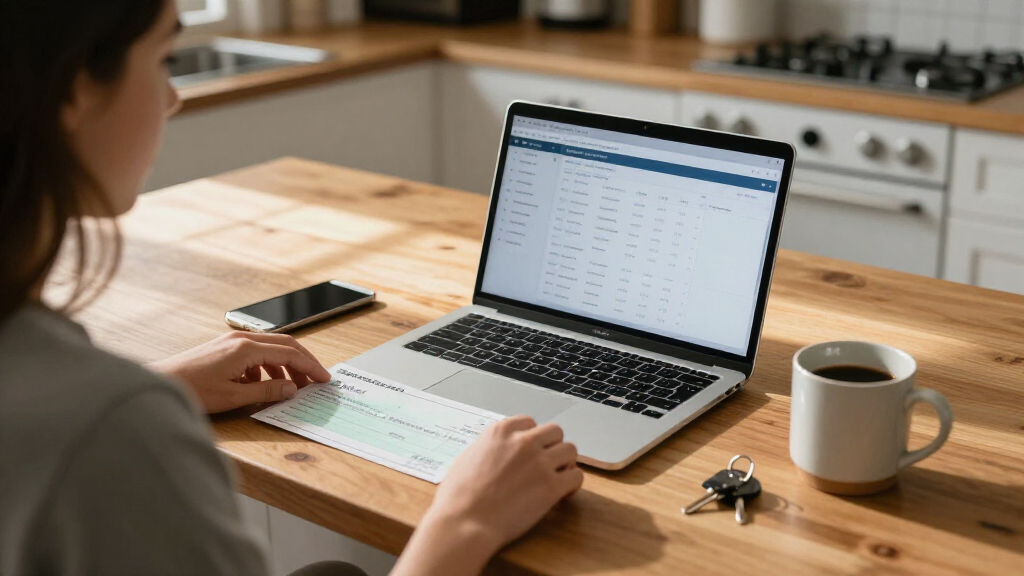
A Kiplinger report describes practical options for depositing an inheritance check when a bank’s mobile-deposit limit or lack of nearby branches creates problems. It recommends contacting the bank or executor, then temporarily holding the money in an appropriate deposit account while deciding on longer-term goals. Account terms, tax implications and protections depend on the individual circumstances and institution.
A Kiplinger report advises people who receive an inheritance check to contact their bank about deposit options if the amount exceeds mobile-deposit limits or they lack access to a branch. The report also suggests temporarily keeping the funds in a suitable deposit account while the recipient considers financial goals, rather than rushing into a long-term decision.
The report describes a case in which a Kiplinger colleague received an inheritance check but could not deposit it through a mobile app and did not live near a branch of their bank. The report says the colleague’s bank suggested sending the check overnight by certified mail, which can provide tracking and proof of delivery. It does not specify the check amount, bank, or the bank’s precise deposit rules.
People who are uneasy about mailing a check can call their bank and explain the situation, according to the report. It also identifies two alternatives: asking whether a partner institution, including a credit union’s partner, can accept an in-person deposit; or asking the estate’s executor whether the check can be canceled and the inheritance sent by wire. Those options depend on the institutions and executor agreeing and being able to arrange them.
In the reported case, the recipient’s brokerage firm arranged for someone to collect the check at home. Kiplinger characterizes this as an uncommon fallback, not a service every bank or brokerage offers. After depositing the funds, the report recommends taking time to choose next steps, with high-yield savings accounts, money market accounts and short-term certificates of deposit among the cash-holding options it discusses.
Avoiding Delays With a Large Check
An inheritance check may arrive during a period of grief, while the recipient is also dealing with unfamiliar banking procedures. A deposit limit or distance from a branch can delay access to the money. Calling the bank before mailing or traveling may clarify the available method, required endorsements, processing time and any holds that could apply.
Choosing where to keep the funds also has practical consequences. Savings accounts and money market accounts can offer access subject to account terms, while a CD generally locks money for a stated term. The report notes that money market accounts may limit some transactions and suggests short CDs as a way to defer a longer-term decision. These are options, not individualized recommendations: rates, withdrawal rules and fees vary, and cash products do not all provide the same access.
The report says to check for FDIC insurance and states that coverage is up to $250,000 per account holder. Actual coverage depends on ownership category and how deposits are held, so recipients with substantial sums should verify coverage with the bank or the FDIC. Taking time to confirm the deposit and account details can help prevent avoidable errors before making larger financial decisions.
high-yield savings account for inheritance funds
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
The Check Is Only the First Step
The source is a Kiplinger personal-finance report built around a colleague’s experience with a large inheritance check. It presents practical suggestions rather than a universal banking rule. Its reference to checks above $10,000 says most banks will not accept them for mobile deposit, but the report does not identify a survey or provide a list of banks. Mobile-deposit thresholds are institution-specific; recipients should check their own bank’s current policy rather than assume a single limit applies everywhere.
The report’s proposed sequence is to resolve the deposit method, place the money somewhere appropriate for short-term holding, then define goals. It suggests consulting a financial adviser or personal banker for help with matters such as debt, saving, investing, retirement, taxes and estate planning. It recommends looking for an adviser who acts as a fiduciary, has a sound reputation, asks about the client’s goals and offers services that fit their needs. These points are the report’s guidance, not a finding that every inheritance requires professional advice.
The source also advises comparing online deposit accounts, saying they may offer higher annual percentage yields and lower fees. Those comparisons can change over time and depend on provider and account conditions. Recipients should review current rates, minimum balances, withdrawal restrictions and deposit insurance directly with an institution before moving money.
“If you don’t want to mail your check, contact your bank directly to explain your situation.”
— Kiplinger report
money market account for large deposits
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Bank Rules and Personal Details Vary
The report does not name the bank, brokerage firm or executor involved, nor does it say how long the check took to clear or whether the colleague used the suggested mailing method. Its statement that most banks restrict mobile deposits above $10,000 is not tied to a named survey or specific institutions. Individual deposit limits and holds vary, so the recipient must confirm current requirements with their bank.
It is also unclear whether a particular executor can cancel a check and issue a wire, how quickly that might happen, or what fees could apply. The supplied report does not address the tax treatment of a specific inheritance, the recipient’s state or country, or whether the check represents cash, proceeds from an asset sale, or another distribution. Those details can affect what questions the recipient should ask an estate professional or tax adviser.
Account rates, insurance coverage and withdrawal terms can change. The article’s account suggestions should not be read as guarantees of a particular return or as a substitute for reviewing the institution’s current disclosures.
short-term certificate of deposit (CD)
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Confirm the Deposit Plan First
The immediate next step is to contact the bank or brokerage using a verified phone number and ask how it will accept the check, what endorsement or documentation is needed, and whether a hold will apply. If mailing is the chosen route, confirm the correct address and delivery procedure; the Kiplinger report recommends certified mail for tracking and proof of receipt. Do not send the check to an address supplied in an unsolicited message.
If the bank cannot accept it conveniently, ask about partner branches or whether the executor can arrange a wire in place of the check. Once deposited and available, compare account terms before choosing a temporary home for the funds. The recipient can then set priorities and consult a qualified adviser if needed. The source provides no further scheduled update or deadline for the case it describes.
inheritance check deposit insurance
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Key Questions
What should I do first after receiving an inheritance check?
Contact the bank or brokerage that will receive the deposit. Ask about its check limits, accepted deposit methods, endorsements, required documents and any hold on access to the funds.
Can I mail an inheritance check to my bank?
The Kiplinger report says its colleague’s bank suggested overnighting the check and recommends certified mail to track it and document delivery. Confirm the bank’s address and mailing procedure directly before sending anything; the report does not establish that every bank accepts mailed checks.
What if I do not live near a branch?
Ask whether the bank works with a nearby partner institution, whether it accepts a mailed deposit, or whether the estate’s executor can arrange a wire instead. The options depend on the bank, executor and estate process.
Where can I keep the money while I decide what to do?
The report lists high-yield savings accounts, money market accounts and short-term CDs as possible places to hold cash. Compare current rates, fees, access rules, term lengths and deposit protection before choosing; a CD may restrict access until maturity or impose an early-withdrawal penalty.
Should I hire a financial adviser?
The report suggests considering an adviser or personal banker, particularly if the inheritance creates unfamiliar planning decisions. It recommends checking credentials, reputation, services and whether the adviser acts as a fiduciary. The need for advice depends on the recipient’s circumstances.
Source: rss
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.