TL;DR
A Kiplinger personal-finance commentary argues that financial strength depends not only on budgets and portfolios but also on how people make decisions under uncertainty. Its examples show how reflecting on values and emotional responses may help families align financial choices with longer-term priorities; the article does not present research proving that these practices improve financial outcomes.
A Kiplinger personal-finance commentary argues that self-awareness and emotional steadiness can shape financial decisions alongside budgets, investment choices and tax planning. The author describes Brighton Jones’ Mindful, Emotional and Social Intelligence framework and offers examples of clients using reflection to weigh financial trade-offs, while the source provides an advisory framework, not evidence from a controlled study that mental fitness by itself improves financial results.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
The author, who writes from experience working with individuals and families, calls this capacity “mental fitness”: understanding one’s own priorities and responding to uncertainty thoughtfully. At Brighton Jones, the author says, colleagues use the MESI framework to help clients consider how wealth can support a meaningful life. The article’s central argument is that the quality of a financial choice depends partly on the thinking and emotions behind it.
One example concerns a couple weighing a job offer that would have doubled one partner’s income but required moving across the country. Their parents, both in their late 70s, lived nearby and relied on the couple for regular help. After considering the financial upside and the family responsibilities, they declined the offer, the author says. The anecdote illustrates a values-based trade-off; it does not establish that turning down the job was financially better.
The commentary also describes a family that reconsidered contributions to their children’s 529 college-savings plans after market declines and alarming headlines. After reflecting on whether their long-term goals had changed, they continued contributing as planned. The author presents the decision as an example of recognizing short-term fear, not as individualized investment guidance or a guarantee about market performance.
How Reflection Can Shape Money Choices
The framework matters because financial decisions often involve more than comparing returns or expenses. Choices about employment, retirement, education savings, charitable giving and family wealth can also involve relationships, identity and personal priorities. Taking time to identify those factors may help people understand what they are choosing between and avoid treating a short-term emotional response as though it were a change in long-term goals.
The article recommends pausing between an event and a decision: describe what happened, identify the values or concerns involved, name the emotions present, and examine the assumptions shaping the response. That process could make a conversation more deliberate, particularly when uncertainty or strong feelings are present. It does not remove financial risks, replace a financial plan, or show that every values-led choice will produce a better monetary outcome.
The distinction is relevant to readers because financial success and personal satisfaction are not automatically the same. A plan may be mathematically sound yet fail to account for a person’s priorities, while a choice that feels meaningful can still carry financial costs. The commentary encourages readers to make those trade-offs explicit rather than assuming that the highest income or largest portfolio is always the right measure of success.
Products Worth Considering

Apple Mac mini Desktop Computer with M6 Chip (2026)

FLEXISPOT Electric Adjustable Workbench, 48 x 30 in, Maple
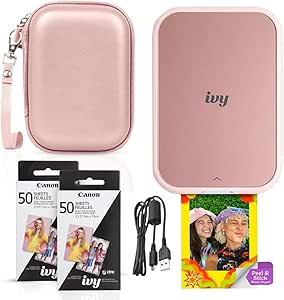
Canon IVY 2 Mini Photo Printer Bundle, Blush Pink
As an affiliate, we earn on qualifying purchases.
The MESI Framework and Its Examples
The source is a personal-finance commentary published by Kiplinger; the supplied material does not include a publication date. Its author connects the advice to work with clients at Brighton Jones, a wealth-management firm, and describes MESI as a framework spanning mindful, emotional and social intelligence. The article presents the framework as an approach used in client conversations, rather than as a formally evaluated intervention.
Beyond the job and college-savings examples, the author recounts a business founder who began making occasional charitable gifts without a longer-term plan. After reflecting on the role a teacher and scholarship program had played in her own life, she incorporated education-focused giving into her plan and involved her children in grant decisions, according to the commentary. The example illustrates how stated values may influence the structure of a financial plan.
Across the examples, the author suggests checking whether spending, time commitments and giving reflect stated priorities. Proposed habits include brief daily reflection, scheduled pauses, uninterrupted thinking time and regular reviews of whether personal values have changed. The source does not report measured results from these practices or compare them with other planning methods.
““The quality of a financial decision depends on the quality of the thinking behind it.””
— Kiplinger commentary author
What the Commentary Does Not Establish
The supplied article is based on the author’s professional perspective and client anecdotes. It does not provide research data, outcome measures or a comparison group showing that the MESI framework or reflection habits lead to stronger returns, higher savings, or improved financial security. The client examples are illustrative and cannot establish how similar decisions would work for other households.
The source also does not specify how the framework is measured, how often it is used, or what results clients experienced over time. It offers no individualized assessment of the job, 529-plan or charitable-giving scenarios. Readers’ financial circumstances, obligations and tolerance for risk differ, and the article does not resolve those case-specific considerations.
Applying the Ideas to a Financial Plan
The commentary does not announce a new policy, product or scheduled follow-up. Its suggested next step for readers is to review whether their financial decisions and everyday use of time reflect their priorities, and to pause before making consequential choices under pressure. The author recommends revisiting values periodically, since priorities may change.
For decisions involving investments, taxes, education savings, retirement or giving, the article’s reflection questions are best understood as prompts for planning conversations, not substitutes for reviewing financial details. Whether this approach produces measurable benefits remains untested in the source. Any assessment of its impact would require evidence beyond the anecdotes presented.
Key Questions
What does the article mean by mental fitness?
The author uses mental fitness to describe self-awareness and the ability to handle uncertainty when making financial decisions. The commentary connects this idea to Brighton Jones’ Mindful, Emotional and Social Intelligence framework.
Does the source prove that mental fitness improves financial returns?
No. It offers professional observations and client examples, but reports no study, measured outcomes or comparison showing that the framework improves investment returns or other financial results.
What reflection process does the author recommend?
The author suggests describing the event, identifying the values and emotions involved, and examining the thoughts or assumptions shaping a response before deciding what to do.
Is this individualized financial advice?
No. The commentary presents general prompts and examples, not recommendations tailored to a reader’s finances. Decisions about investments, taxes, savings or giving depend on individual circumstances.
Source: rss