Choosing personal finance budgeting software comes down to how you want to manage money: keep the process focused, plan for financial independence, or bring many parts of your finances into one view. I rank Quicken Classic Deluxe first for buyers who want budgeting alongside banking, debt, investment, and property tracking. SavePoint is my pick for offline budgeting and FIRE planning, while Dave Ramsey’s Personal Finance Software suits buyers who want a simpler money-management approach.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
The main tradeoff is breadth versus focus. Quicken covers more financial categories but requires a one-year subscription. SavePoint stores data locally and offers long-range planning tools, though its use is limited to two devices and updates apply to the purchased version. Ramsey’s software is identified as Financial Peace Personal Finance Software, but the supplied product information is much less detailed, so buyers have fewer specifics to compare before choosing.
Key Takeaways
- Quicken Classic Deluxe is the broadest option here, combining budgets with banking, credit cards, debt, investments, and property tracking.
- SavePoint is the clearest fit for offline use, local data storage, cash-flow analysis, and FIRE scenarios such as Lean, Traditional, Fat, and Coast.
- Dave Ramsey’s Personal Finance Software is positioned around taking control of money, but the provided details do not specify platform, reporting, or account-linking capabilities.
- Quicken’s access lasts one year, while SavePoint is described as a one-time purchase with updates for the purchased version.
- The best match depends on whether a buyer values broad financial coverage, privacy and independence planning, or a more focused money-management tool.
| Quicken Classic Deluxe Personal Finance Software for New Subscribers, 1-Year Online Code for PC and Mac | 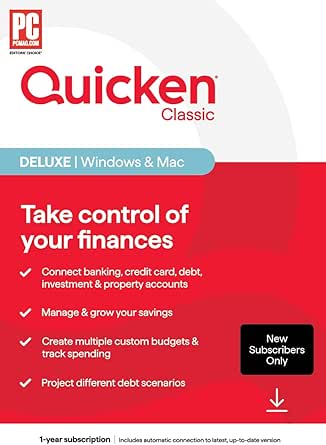 | Best Overall for Whole-Finance Budgeting | Subscription: 1 year | Platform: PC and Mac | Delivery: Online code | VIEW LATEST PRICE | See Our Full Breakdown |
| SavePoint Personal Finance Software for Budgeting and FIRE Planning, with Monte Carlo Simulations and 8GB USB Drive |  | Best for Offline Budgeting and FIRE Planning | Storage: Local-only; operates offline | Compatibility: Windows PC and Mac | Included accessory: 8GB USB drive | VIEW LATEST PRICE | See Our Full Breakdown |
| Dave Ramsey’s Personal Finance Software, Version 5.3 |  | Best for a Focused Money-Control Approach | Product identity: Financial Peace Personal Finance Software | Version: 5.3 | Stated purpose: Personal finance and money management | VIEW LATEST PRICE | See Our Full Breakdown |
More Details on Our Top Picks
Quicken Classic Deluxe Personal Finance Software for New Subscribers, 1-Year Online Code for PC and Mac
Quicken Classic Deluxe earns my top spot because it places budgeting beside the other financial categories that often shape a household’s spending plan. It is described as covering banking, credit cards, debt, investments, and property, as well as custom budgets and spending tracking. That wider view can help a buyer connect a monthly spending decision with debt balances or investment activity instead of treating the budget as an isolated worksheet.
Its debt-scenario comparisons are a practical distinction from Dave Ramsey’s software, whose supplied description does not specify debt tools, and from SavePoint, which emphasizes offline tracking, reports, and FIRE analysis. Buyers who want a single place for budgeting and several financial categories may find Quicken’s breadth easier to work with than a focused planning tool. It is the strongest general-purpose choice in this lineup based on the stated feature set.
The tradeoff is access. This is a one-year subscription delivered as an online code, and the listing is for new subscribers. Someone seeking software with a described one-time license may prefer SavePoint, while a buyer primarily concerned with local-only data storage may also favor SavePoint’s offline design. The supplied details do not explain how Quicken connects to institutions or what happens to access after the subscription ends, so buyers should check current terms before relying on it as a long-term archive.
I recommend Quicken for a new subscriber who wants budgeting to sit alongside debt and asset tracking, rather than for someone who needs only a simple spending plan. It has the broadest stated scope here, but that scope is most valuable when the buyer will actually use those categories. If privacy-first offline operation or detailed FIRE scenarios are the main goals, SavePoint is the more tailored pick.
Pros:- Combines budgeting and spending tracking with banking, credit cards, debt, investments, and property.
- Custom budgets can support a more personal spending plan than a fixed template alone.
- Debt-scenario comparisons add a planning tool not specified for the other two products.
- Available for PC and Mac.
Cons:- The supplied access term is limited to one year.
- This edition is intended for new subscribers.
- The product details do not specify offline use, local data storage, or what happens to access after the subscription.
Best for: New subscribers who want budgets, spending tracking, debt scenarios, investments, banking, and property represented in one personal-finance program.
Not ideal for: Buyers who want a perpetual license, offline-only operation, or a budgeting tool with clearly stated long-term access beyond the one-year subscription.
- Subscription:1 year
- Platform:PC and Mac
- Delivery:Online code
- Subscriber eligibility:New subscribers
- Budgeting:Custom budgets and spending tracking
- Financial coverage:Banking, credit cards, debt, investments, and property
- Debt planning:Compare debt scenarios
Our verdict“Choose Quicken Classic Deluxe if you want budgeting connected to a broad household-finance picture and accept a one-year subscription.”
SavePoint Personal Finance Software for Budgeting and FIRE Planning, with Monte Carlo Simulations and 8GB USB Drive
SavePoint is the most distinct choice in this group: it is described as offline software that stores financial data locally, while also covering budgeting, cash flow, balance sheets, and financial independence planning. That combination fits buyers who want a private, self-contained planning setup rather than a tool centered on a broad connected view. The included 8GB USB drive gives the package a physical storage accessory, though the provided details do not explain how backups or moving data between devices work.
Its strongest advantage over Quicken Classic Deluxe is the depth of its stated long-range planning. SavePoint includes Monte Carlo simulations and supports Lean, Traditional, Fat, and Coast FIRE strategies. Those tools can help a buyer examine how a spending plan relates to financial independence goals, rather than stopping at monthly categories. Its reports, variance analysis, cash-flow tracking, and Sankey diagrams also give users several ways to review where money moves. The listed unlimited accounts and transactions may suit people maintaining detailed records.
SavePoint also supports Windows PC and Mac, up to two devices, eight languages, and more than 150 currencies. Those details give it a broader international and multi-currency profile than the other listings establish. Compared with Dave Ramsey’s software, its described feature set is far more specific, which makes it easier to judge before purchase. The limitations are equally concrete: use is capped at two devices, and updates are included for the purchased version rather than described as continuing access to every future release.
This is my pick for a buyer who values offline access and independence planning more than a one-place view of banking, investments, and property. Quicken has the wider household-finance coverage, while SavePoint offers the clearer local-data and FIRE-planning case. Buyers who mainly want conventional budgeting and do not expect to use simulations, reports, or balance sheets may find SavePoint’s breadth unnecessary.
Pros:- Operates offline and stores financial data locally.
- Combines budgeting, variance analysis, cash flow, balance sheets, and more than ten report types.
- Monte Carlo simulations support Lean, Traditional, Fat, and Coast FIRE strategies.
- Supports Windows PC and Mac, eight languages, and more than 150 currencies.
Cons:- Use is limited to up to two devices.
- Updates are included for the purchased version, not described as an ongoing all-version plan.
- Its feature-rich planning approach may be more than a buyer needs for basic monthly budgeting.
Best for: Privacy-minded budgeters and FIRE planners who want offline local storage, detailed reports, cash-flow tools, and multiple currency support on up to two devices.
Not ideal for: People who need more than two devices, want ongoing updates beyond the purchased version, or prefer a single program described as covering banking, investments, and property.
- Storage:Local-only; operates offline
- Compatibility:Windows PC and Mac
- Included accessory:8GB USB drive
- Device limit:Up to 2 devices
- FIRE strategies:Lean, Traditional, Fat, and Coast
- Languages and currencies:8 languages; 150+ currencies
- Finance tools:Budgeting, variance analysis, balance sheets, cash flow, Sankey diagrams, and 10+ report types
- Accounts and transactions:Unlimited
- License:One-time purchase; updates for the purchased version
Our verdict“Choose SavePoint when offline privacy and FIRE analysis matter more than Quicken’s broader banking, debt, investment, and property coverage.”
Dave Ramsey’s Personal Finance Software, Version 5.3
Dave Ramsey’s Personal Finance Software, identified as Financial Peace Personal Finance Software, is the most focused and least fully documented choice in this roundup. The supplied description says it is designed to help users manage their money and take control of it. That broad aim may appeal to someone seeking a budgeting-oriented starting point without making FIRE simulations or extensive investment and property tracking the center of the decision.
Its main difference from Quicken Classic Deluxe is apparent in the amount of scope described. Quicken explicitly lists banking, credit cards, debt, investments, property, custom budgets, spending tracking, and debt comparisons. Ramsey’s listing does not state whether it includes those tools, so buyers should not assume feature parity. Compared with SavePoint, it also lacks supplied details about offline storage, reports, cash-flow views, currencies, or device limits. That makes it harder to judge how well it will fit a specific household or computer setup.
The product’s identity and version number are given, but the provided information does not establish its supported operating systems, account connection options, update policy, licensing arrangement, or current compatibility. Those omissions matter for budgeting software because a buyer needs to know how data is entered, where it is stored, and whether the program will run on their devices. I would verify those points in the current listing before choosing it, especially if the software will become the main record of household spending.
I place it third because its stated purpose is relevant, but the available evidence supports fewer confident comparisons than either SavePoint or Quicken. That is not a claim that it lacks useful functions; it is a reason for a cautious purchase decision. This option makes the most sense for buyers specifically drawn to the Financial Peace identity and willing to confirm the practical details. If the priority is a clearly described set of tools, Quicken or SavePoint is easier to match to a defined need.
Pros:- Designed to help users manage money and take control of their finances.
- Identified as Financial Peace Personal Finance Software, giving buyers a clear product approach to investigate.
- Version 5.3 is specified in the product title.
Cons:- The supplied description does not list specific budgeting workflows or reporting tools.
- Platform compatibility, storage approach, and account connection details are not specified.
- The provided information does not describe licensing or update terms.
Best for: Buyers interested in Financial Peace Personal Finance Software who want a money-management option and are prepared to confirm compatibility and features before purchase.
Not ideal for: Anyone who needs verified platform support, offline storage details, explicit reporting tools, or a clearly stated license and update policy before choosing software.
- Product identity:Financial Peace Personal Finance Software
- Version:5.3
- Stated purpose:Personal finance and money management
- Budgeting workflow:Not specified in the supplied details
- Platform compatibility:Not specified
- Storage and connectivity:Not specified
- License and updates:Not specified
Our verdict“Consider this option if its Financial Peace approach is your priority, but verify its compatibility and exact budgeting tools before buying.”
How We Picked
I ranked these options by how directly their described capabilities support personal budgeting and day-to-day financial decisions. A budgeting program should help a buyer understand where money goes, plan upcoming spending, and make useful adjustments. I also looked at the surrounding tools: cash-flow views, debt planning, investments, property, and long-range independence projections can make a budget more useful, but they matter differently to different households.
Quicken Classic Deluxe ranks first because its stated scope connects budgeting with several major parts of a household’s finances. That breadth can reduce the need to maintain separate systems for debt, investments, and property, although it comes with a one-year subscription and is intended for new subscribers. SavePoint ranks second because its offline operation, local storage, reporting, and FIRE simulations create a distinct planning advantage. Its two-device limit and version-based updates are meaningful boundaries.
Dave Ramsey’s software ranks third not because the supplied description establishes that it is inferior, but because it offers fewer verifiable decision points. The available information identifies its purpose and version, but does not describe platform support, budgeting workflows, reports, account connections, or licensing terms. I treat that lack of detail as a buying uncertainty rather than assuming capabilities that have not been supplied. I have not inferred features beyond the product descriptions and listed specifications.
For this comparison, I give weight to useful budget context, understandable tradeoffs, and fit for a particular buyer. I do not treat a longer feature list as an automatic win: offline privacy may matter more than investment tracking for one person, while another may prefer a connected whole-finance view. The rankings reflect how much decision-making support each option’s stated details provide.
Factors to Consider When Choosing Personal Finance Budgeting Software
I would choose budgeting software by matching its working style to the decisions I need it to support. A budget can be a simple spending plan, a private offline record, or one part of a larger financial picture. These options differ most in breadth, privacy, planning depth, and how much product information is available.Decide whether your budget needs a wider financial picture
If I want a budget connected to other household accounts and obligations, Quicken Classic Deluxe has the broadest stated coverage in this lineup. It includes banking, credit cards, debt, investments, and property, with custom budgeting and spending tracking. This is useful when spending choices depend on more than the month’s expenses: debt payoff, savings, investments, and property can all affect the plan.
That wider scope is not automatically necessary. A buyer who only wants to plan spending may not benefit from maintaining categories they do not use. SavePoint also covers several financial areas, especially balances and cash flow, but its distinct strength is offline reporting and independence planning. Ramsey’s listing gives much less information about its specific functions, so I would verify the scope before treating it as a full-featured alternative to Quicken.
Treat privacy and access as separate decisions
SavePoint is the clear offline choice because the description says it operates offline and stores data locally. That can suit someone who does not want their budgeting process to depend on an internet connection. It also means the buyer should think about how to protect and back up local records; the supplied information does not spell out backup procedures. The included USB drive is an accessory, but it should not be taken as proof of a particular backup system.
Quicken’s description does not specify offline operation or local-only storage, and the Ramsey listing does not state how data is stored. I would not infer privacy or connectivity behavior from the product names. Ask how transactions enter the program, where information resides, and how records can be exported or retained. Separately, note the access terms: SavePoint is described as a one-time purchase with updates for the purchased version, while Quicken is a one-year subscription for new subscribers.
Match planning tools to your time horizon
For monthly budgeting, custom categories and spending tracking may be enough. For decisions that stretch over years, SavePoint adds Monte Carlo simulations and four FIRE strategies: Lean, Traditional, Fat, and Coast. It also lists cash-flow analysis, balance sheets, variance analysis, Sankey diagrams, and more than ten report types. These features are most useful when a buyer expects to review scenarios and patterns, not just record expenses.
Quicken takes a different planning route by including debt-scenario comparisons alongside its broader financial categories. That may fit someone deciding how to approach balances while maintaining a household budget. Ramsey’s supplied details do not describe comparable planning tools. I would choose based on the decisions I actually need to make; an elaborate simulation package can add complexity without helping a buyer who only wants a straightforward spending routine.
Check device, platform, and household fit
SavePoint explicitly supports Windows PC and Mac, but limits use to up to two devices. That may be enough for a personal computer and a second household device, but it could be restrictive for someone expecting to work across a larger device set. Its support for eight languages and more than 150 currencies is a notable fit advantage for multilingual or multi-currency finances.
Quicken also lists PC and Mac compatibility, while the product information for Ramsey’s software does not specify a platform. For any option, confirm that the current software works with the devices and operating systems you use. If more than one person will maintain the budget, check how shared access works; the supplied descriptions do not explain collaboration or simultaneous use.
Use listing detail as part of the buying decision
Budgeting software becomes a record of financial decisions, so I value clear product information. SavePoint and Quicken provide specific lists of tools and limitations, making it easier to compare them against a buyer’s needs. The Ramsey entry identifies its purpose and version but leaves important practical questions unanswered, including compatibility, storage, features, and licensing. That does not establish that the software is unsuitable; it means a buyer should request or confirm those details before committing.
Before choosing, write down the three tasks you expect the software to handle most often. For example, tracking weekly spending, reviewing debt payoff options, or modeling a retirement timeline will point toward different tools. Choose for your repeated decisions, not for the longest feature list. A product that fits your routine is more useful than one whose advanced tools remain unused.
Frequently Asked Questions
Which option is best for budgeting and managing several types of finances?
Quicken Classic Deluxe is the strongest match if you want budgeting alongside banking, credit cards, debt, investments, and property tracking. It also includes debt-scenario comparisons, which extend its role beyond expense tracking. SavePoint has substantial planning and reporting tools, but its description emphasizes offline use and FIRE planning rather than the same broad household-finance coverage.
Which software is best for offline budgeting and local data storage?
SavePoint is the only option here explicitly described as operating offline and storing data locally. That makes its privacy and connectivity profile easier to assess than the other listings, whose storage behavior is not specified. Buyers should still confirm how they can back up and move their records, since those procedures are not detailed in the supplied product information.
Which option includes tools for financial independence planning?
SavePoint is the clear choice for stated FIRE planning. Its Monte Carlo simulations cover Lean, Traditional, Fat, and Coast strategies, and its broader toolset includes cash flow, balance sheets, and multiple report types. Quicken is described as including debt-scenario comparisons, but the supplied details do not list FIRE simulations; Ramsey’s listing does not specify long-range planning tools.
Is Quicken Classic Deluxe a one-time purchase?
No. The provided listing describes a one-year subscription delivered as an online code for new subscribers. Buyers who prefer a one-time purchase should compare that term with SavePoint, which is described as a one-time purchase with updates for the purchased version. I would check the current terms before buying, including what happens when the subscription period ends.
What should I verify before buying Dave Ramsey’s Personal Finance Software?
The supplied information identifies it as Financial Peace Personal Finance Software, Version 5.3, but does not specify its platform, storage method, account connections, budgeting workflow, reports, or license and update terms. I would verify those points against the current product information before relying on it as a main budgeting tool. Quicken and SavePoint have more clearly described feature sets, which makes their fit easier to judge from this comparison.
Conclusion
For broad personal-finance coverage, I recommend Quicken Classic Deluxe to new subscribers who want budgeting connected to debt, investments, banking, credit cards, and property. Choose SavePoint if offline local storage, cash-flow reports, multiple currencies, or FIRE scenarios matter most, and if the two-device limit fits your setup. Consider Dave Ramsey’s Personal Finance Software when the Financial Peace approach appeals to you, but confirm its platform, specific budgeting tools, and license terms first. My ranking favors the options whose stated features make their budgeting role easiest to evaluate; the right choice is the one that supports the money decisions you will actually revisit.